
Park Hill Neighborhood Guide11.04.2026
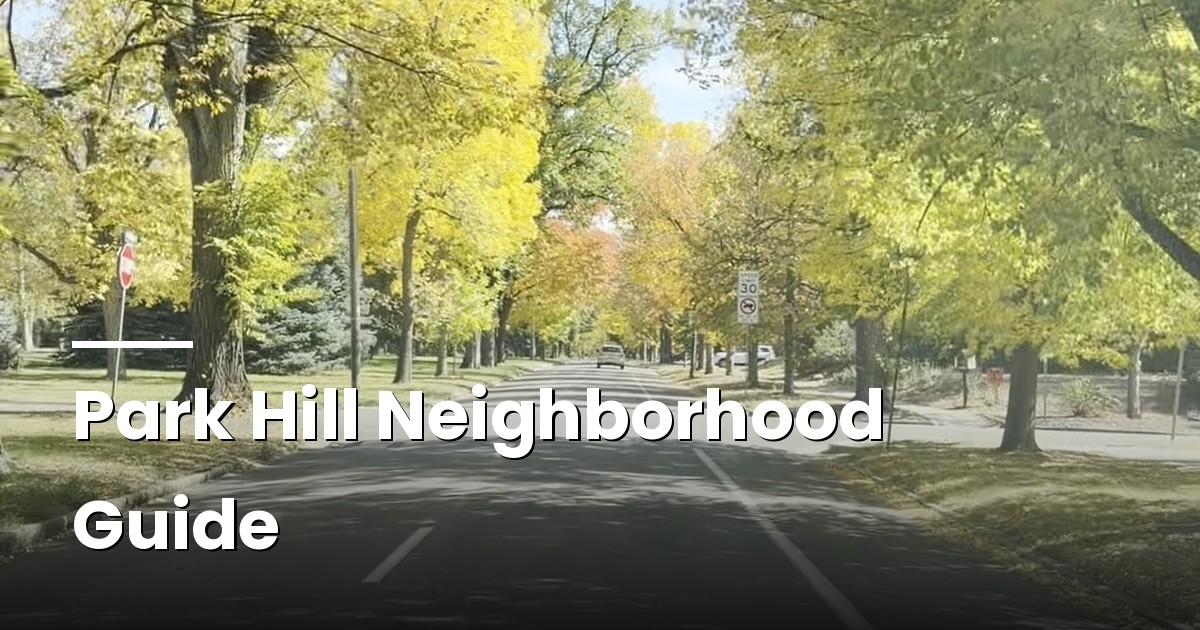
Thinking of calling Park Hill home? Great idea! I've collected some of the details you'll want to know before moving to [...]
 A buyer I talked with last week had the whole thing figured out. She'd wait until rates dropped, then jump in and save a fortune. It's a smart-sounding plan. It's also the plan most buyers are running right now. In a recent national survey, 62% of buyers said they're waiting for mortgage rates to fall before they buy. That's almost two out of every three. So if you've been sitting on the sidelines watching Denver mortgage rates, you're in good company.
But waiting has its own costs, and they're worth understanding before you decide. Here's where rates actually sit.
As of late July, the average 30-year fixed rate hit about 6.58%, the highest point of 2026. Earlier this month rates dipped a little, then bounced right back up. Part of the reason is tension overseas pushing oil prices higher, which stirs up worries about inflation. When inflation worries rise, mortgage rates usually follow. So the honest answer to "will rates drop soon?" is: nobody knows.
Betting your timeline on it is a gamble, not a plan.
Now here's the part that gets missed. While you wait for a lower rate, two other things are happening. First, home prices in Denver are holding near record levels. The average price sits around $640,000, up 2.5% from last year. Second, you're paying rent or a mortgage somewhere in the meantime, and none of that builds your own equity. Let's say you wait a year and rates drop half a point. Sounds like a win. But if that same home costs $20,000 more by then, the lower rate barely covers the higher price. You end up in roughly the same spot, just twelve months later.
Sometimes waiting works. Sometimes it quietly costs you. There's also good news hiding in these numbers. The Denver market has shifted toward balance. That means less of the wild bidding-war pressure we saw a few years back. New listings have been tight, but serious sellers are still out there, and buyers who show up prepared have room to negotiate. A slower market can actually be a friendlier one for a patient buyer. And rates aren't forever.
This is the thing I remind people most. You lock a price when you buy, but you don't lock a rate for life. If mortgage rates drop down the road, you can refinance. Buying now doesn't mean you're stuck at 6.58% until 2056.
So how do you decide? Start with your own numbers, not the headlines. Look at what you can comfortably afford at today's Denver mortgage rates, not the rate you're hoping for. Factor in property taxes and any HOA dues, because those have climbed too. If the monthly payment works for your life right now, the rate is less scary than it looks. If it doesn't, waiting a bit is the right call, and there's no shame in that.
The buyers who do best aren't the ones who time the market perfectly. They're the ones who know their real budget and move when the right home shows up. If you're trying to figure out whether the math works for you right now, I'm happy to run the actual numbers on a home you like. You can email me anytime, or follow along on Instagram @madisonspanglerhomes where I break down this stuff week to week.
 If you're choosing a Denver real estate agent this year, here's what actually separates a great one from a licensed one.
Neighborhood knowledge you can test. Denver isn't one market. Park Hill behaves differently than Cherry Creek — different buyers, different price bands, different quirks (hello, sewer lines under 100-year-old trees). Ask a simple question: "What's happening in my desired neighborhood right now?" A strong agent answers with specifics — recent sales on nearby streets, days on market, what buyers are asking for in this exact market.
A pricing opinion backed by data — even when it stings. Some agents win listings by naming the biggest number in the room, then walk the price down month after month. It's called buying the listing, and it costs sellers real money. Overpriced homes sit, and homes that sit get lowball offers. Look for the agent who shows you the comps and explains their logic, even if they ultimately tell you a number you maybe didn't want to hear.
Full-time attention. Colorado contracts run on strict deadlines — inspection objection, appraisal, loan conditions. Miss one and you can lose rights, or lose the deal. An agent juggling real estate around another job can miss things an agent living in these contracts daily won't. It's a fair question to ask directly: "Is this your full-time work, and how many clients are you serving right now?"
A communication style that matches yours. Some clients want a call; some want a text at 9pm; some want everything in writing. None of that is wrong — but a mismatch gets exhausting over the course of a transaction. Notice how the agent communicates during the interview stage. That's them at their best. It only gets more casual from there.
Negotiation stories, not negotiation slogans. Anyone can say they're a strong negotiator. Ask for a real example: "Tell me about a deal that almost fell apart and what you did." The answer tells you how they think under pressure — which is exactly when you'll need them. And yes — interview more than one. Even if the first meeting feels great. Talking to two or three agents costs you a few hours and gives you something priceless: contrast. The right agent won't be threatened by that. They'll encourage it, because they know how they compare.
One thing I'd gently push back on: choosing an agent just because they're family, a friend, or the neighbor who mailed you a calendar. Relationships matter — I'd argue they matter most — but they should come with the neighborhood data, the deadline discipline, and the honest pricing conversation attached. You can love someone and still ask them hard questions. A true professional will love that you asked. If you're starting a search — for a home or for an agent — I'd love to be one of your interviews. Email me at madison@corcoranperry.com and bring me all the hardball questions you've got!
 Every year in early spring, my phone starts buzzing with clients asking whether they've already missed their window to sell. They haven't — but the question is a smart one, because in Denver, timing genuinely moves the needle. So here's the honest answer to when the best time to sell a home in Denver actually is, backed by numbers instead of hunches.
The short version: late May through June. Sale metrics put Denver's sweet spot in the second half of May, where listings earn about a 2.9% price premium. Homes listed in June sell for about 4.2% more than average. And speed follows the same pattern: during May and June, Denver homes spend around 20 to 23 days on the market, which is 10 to 15 days faster than the rest of the year.
But why do those months work? Three things stack up at once. The weather turns, so yards and gardens finally look like themselves. The days get longer, so buyers tour after work in daylight. And families with kids are racing a deadline — they want to close and move before the school year starts in August.
Timing your sale so more motivated buyers are competing for your house is the goal. But the "best" time depends on the house. A home near a sought-after school zone sells best in that spring window, when families are shopping hardest. A downtown condo cares less about the school calendar — those buyers shop year-round. And a home with a stunning yard or mountain view should be photographed and listed when that feature is at its peak, even if the calendar says otherwise.
Don't write off winter. Fewer homes hit the market between November and January, which means less competition for yours. The buyers who trudge through snow to a showing aren't just browsing — they're buying. I've seen January sellers do very well simply because they were the best option in a smaller pool of choices.
One thing about right now. This summer, Denver has shifted toward a more balanced market — sales have slowed and buyers have more leverage than they've had in years. Sellers are still getting about 99% of asking price, but the days of ten offers over the weekend are mostly behind us. That makes pricing and preparation matter more than the listing date. A well-prepped home priced right in October will beat an overpriced one in May, every time.
If you're flexible and aiming to put your home on the market next spring, start counting backward. A late-May listing means photos in early May, which means paint, repairs, and decluttering in March and April. The sellers who win the spring market started long. before spring. If you're wondering where your home fits in all this — what it's worth today, and what a few months of waiting might actually gain you — email me at madison@corcoranperry.com and we'll map out your timeline together.
 Let's break it down in plain English. A contingent offer is an accepted offer with conditions attached. The buyer is saying: "I'll buy your house — as long as a few specific things check out first." Those conditions are called contingencies, and until they're cleared, the transaction won't close. Think of it as an engagement, not a wedding. Serious, but not final.
Typically, when we talk about a contingent offer, we're talking about the need to sell one house before buying another. But in reality, there are several types of standard contingencies. Here are the four contingencies you'll see most often in Colorado contracts.
Inspection. The buyer hires an inspector to look at the roof, furnace, sewer line, and everything in between. If something big turns up, the buyer can ask for repairs, ask for money (called a concession), or back out all together.
Appraisal. The lender sends an appraiser to confirm the home is worth what the buyer agreed to pay. If it appraises low, the two sides renegotiate, the buyer brings more cash to the table, or the deal can end.
Financing. The buyer's loan has to receive final approval. Pre-approval is a strong start, but the lender doesn't fully commit until underwriting is done.
Home Sale. Some buyers need to sell their current home before they can close on the next one. This is the contingency sellers scrutinize hardest, because it ties your sale to a house you've never seen and priced outside of their control.
In Colorado, each contingency comes with a deadline written right into the contract. Miss a deadline, and rights can expire — which is exactly why these dates get tracked so carefully. If you're a buyer and the home you love just went under contract before you were able to jump on it: it's not necessarily over. Deals do fall apart — inspections surprise people, loans hit snags. You can often submit a backup offer, which puts you first in line if the current contract cracks. It costs nothing to ask.
If you're a seller weighing a contingent offer: don't panic at the word. Nearly every offer has contingencies — an offer with none would be unusual. What matters is which contingencies, how long the deadlines run, and how solid the buyer's financing looks. A contingent offer from a well-qualified buyer with tight deadlines often beats a slightly higher offer wrapped in loose ones.
Contingencies aren't red tape — they're seatbelts. They exist so nobody gets locked into buying a house with a cracked foundation or selling to a buyer whose loan was never going to close.
 The panic doesn't hit until you're settled into your Airbnb in the mountains: "Did we close the garage?" Nobody remembers. Your stomach drops, and the first two days of vacation are spent refreshing a doorbell camera instead of relaxing.
A simple checklist of items to tackle before vacation fixes that. Fifteen minutes the night before you leave, and you get to actually be gone — not half-home, half-worried.
Here's what I run through before any trip, roughly in order of what can go wrong.Water first. Water causes more vacation-season home damage than anything else — burst supply lines, failed washing machine hoses, a toilet that runs for ten days straight. If you'll be gone more than a few days, consider shutting off the main water valve. At minimum, turn off the valves behind the washing machine, and check under every sink for drips. Set your water heater to vacation mode while you're at it — no reason to heat water for an empty house.
Next up is the thermostat. Don't shut the AC off completely in a Denver summer — big heat swings are hard on wood floors, paint, and anything electronic. Set it around 82-85 degrees instead. In winter, never go below 55; that's your freeze protection for pipes.
Now tackle the smaller stuff. Unplug the toaster, coffee maker, TVs, and chargers — small savings and a reduced fire risk. Put a couple of lamps on timers, so the house looks lived-in after dark. Empty the fridge of anything that won't survive the trip, and take out all the trash. Lock the windows and doors, including the one from the garage into the house. Close the garage door and consider engaging the manual lock - it adds protection and will help you remember that you shut it!
Lastly, pause your mail and package delivery thru USPS, so mail and packages don't pile up on your porch. Better yet, ask a neighbor to grab anything that shows up and park in your driveway once or twice. And lastly, for security purposes, wait to post the vacation photos until you're home. The mountains will still be beautiful in your feed next week.
One bonus step if you want full peace of mind: snap a quick photo of the thermostat, the water valve, and the locked front door on your way out. If the "did we...?" question comes up while you're away, you have the answer in your pocket.
None of this is complicated, but it does require that you set aside the time (and mental capacity). It's too easy to forget these things when you're wrangling suitcases and rushing out the door.
I share quick homeowner tips like this all summer on Instagram — come follow along at @madisonspanglerhomes
 Four office towers in downtown Denver sold this spring for about $4.80 per square foot. Not $480 per square foot. Not even $48 per square foot!
1.8 million square feet of office space, scooped up by a Los Angeles investor for less than the cost of a latte per square foot. If you own a home anywhere in Denver, a headline like that can make your stomach drop. So let's separate what's actually happening downtown from what it means for your house.
The downtown Denver office vacancy rate hit 38.9% in the first quarter of 2026 — an all-time high. But it's really a tale of two downtowns. In upper downtown, near the Capitol, some blocks are more than 46% empty. Down in LoDo, vacancy sits closer to 20%. The buildings hurting most are the older ones — nearly half of the lowest-tier office space now sits dark.
Here's the part that matters for homeowners: offices and homes are two different markets. Offices emptied out because people stopped commuting to a desk. Nobody stopped needing a kitchen and a bedroom. While those towers were selling at fire-sale prices, the median Denver home price rose to $616,000 in June — up from a year earlier — and sellers are still getting about 99% of their asking price. Empty cubicles don't set the value of your house.
Now the interesting part. There are plans to turn those cheap towers into housing. The Denver Energy Center on Broadway is slated to become 386 apartments. High Fidelity Plaza is planned as another 700. And the city is putting real money behind it — the Downtown Denver Development Authority committed $63 million to one conversion this spring.
Studios in the converted buildings are expected to start around $1,700 a month, with a batch of units set aside as affordable housing. In a metro that's short more than 55,000 affordable units, empty towers becoming homes is a rare win-win.
But why should you care if you live in Park Hill or Congress Park? Because more people living downtown means fuller sidewalks, busier restaurants, and safer streets after dark. That energy tends to spill outward into nearby neighborhoods over time — and it supports the small businesses that make this city worth living in.
It won't happen overnight. Most conversion projects won't finish until at least 2027. But the direction matters more than the speed. The takeaway: downtown's office pain is real, but it's not your pain. If anything, the fix — turning dead office space into places people live — could make Denver's core stronger than it was before the pandemic.
 A buyer I talked with last month had been "waiting for rates to drop" for over a year. She'd watched the number tick between 6% and 7% so many times she'd started refreshing rate sites the way some people check the weather. In that year, the house she almost bought went up in value. Her rate never got meaningfully lower.
If you've been holding off on buying because you're waiting for rates to fall, it's worth looking at what's actually happening right now, and what the people who track this for a living expect next.
As of today, the average 30-year fixed mortgage rate sits around 6.4% to 6.7%, depending on the lender. That's come down from the 7%-plus rates buyers were facing in late 2023, but it's not expected to move much lower in the near term. Fannie Mae's latest forecast projects rates holding around 6.4% for the rest of this year. The Mortgage Bankers Association expects something similar, closer to 6.5% through the third and fourth quarters. A recent poll of housing economists found the consensus is rates aren't expected to fall meaningfully anytime soon — inflation is still running above the Fed's target, and the Fed has signaled it's in no hurry to cut rates further.
None of this means rates can't move. They could tick down half a point if the economy shifts, or up if inflation runs hotter than expected. But "wait for it to get better" has been the plan for a lot of buyers for over two years now, and the number has mostly just moved sideways in a fairly narrow band. Meanwhile, home prices in Denver haven't stood still. Waiting for the rate to improve while the price keeps climbing can end up costing more than just buying at today's rate on today's price.
There's a real strategy buried in this, and it's simpler than people expect: buy the house that fits your life and your budget now, and treat the rate as something you can revisit later. If rates do drop in a year or two, refinancing is always on the table — you're not locked into today's rate forever. But you are locked out of today's price if you wait and the market moves without you.
This doesn't mean rushing into a house that doesn't work for you, or stretching your budget to make a deal happen. It just means the rate alone probably shouldn't be the reason you're sitting on the sidelines. If you find the right house and the payment works for your life today, that's usually worth more than chasing a number that may not move much regardless.
If you've been waiting for rates and want to talk through whether it still makes sense to wait, or whether it's time to actually look, I'm happy to run the numbers with you. Let's connect!
 A seller in Congress Park sat on her house for six weeks with no offers before her agent suggested something other than dropping the price. Instead of cutting $10,000 off the list, she offered to fund a 2/1 buydown for the buyer. The house sold two weeks later, at full price.
If you've been house hunting lately, you've probably seen "seller offering 2/1 buydown" in a listing and moved past it without knowing what it meant. It's worth understanding, because it can genuinely change what a house costs you in the first two years — and it's one of the more useful negotiating tools in today's market.
Here's the mechanics. A 2/1 buydown temporarily lowers your interest rate for the first two years of your loan: 2 percentage points lower in year one, 1 point lower in year two, then it returns to your actual note rate in year three and stays there. Say your loan rate is 7%. In year one, you'd pay as if your rate were 5%. In year two, as if it were 6%. From year three onward, you pay the real 7% for the rest of the loan. Your rate on paper never actually changes — the seller (or sometimes the builder) deposits money into an escrow account at closing, and that money covers the difference between what you're paying and what the loan actually costs each month.
This is different from an adjustable-rate mortgage. Nothing here fluctuates with the market. It's a fixed-rate loan the whole way through — you just know exactly when and how much your payment will step up, instead of finding out later.
Where this gets useful is in negotiation. In a market where inventory is up and sellers are having a harder time getting their asking price, a buydown gives sellers a way to make a house more affordable without actually lowering the price on paper. On a $500,000 loan, funding a 2/1 buydown might cost the seller somewhere in the range of $10,000 to $13,000 — similar to what a price cut of that size would cost them, but structured differently. For the buyer, it means two years of real breathing room in the budget: money for movers, furniture, or just easing into a new mortgage payment instead of jumping straight into it.
It's important to note that you still have to qualify for the loan at the full note rate, not the reduced year-one rate — the buydown doesn't help you afford more house, just cushions the first two years. But it can help if you have current expenses (think college loan payments, daycare bills) that will be ending in the next year or two, but you don't want to wait that long to buy.
If you're weighing a buydown against asking for a straight price cut, or wondering whether it makes sense for a house you're looking at, that's worth a real conversation before you write an offer. Let's connect!
 A buyer I worked with last year had $18,000 saved and figured that ruled her out of the market entirely. She'd done the math on a $600,000 house, seen the $120,000 number for 20% down, and quietly stopped looking. Three months later, she closed on a house with 3% down.
That 20% number gets repeated so often that most people never question it. But it's not a rule. It's one option among several, and for a lot of buyers, it's not even the best one.
Conventional loans allow down payments as low as 3% for qualified first-time buyers. FHA loans, backed by the federal government, go down to 3.5%. VA loans, for eligible veterans and active-duty service members, and USDA loans, for certain rural and suburban areas, can go all the way to 0% down. The 20% figure only matters if you want to skip private mortgage insurance, which is a real cost, but it's a monthly fee, not a locked door. Plenty of buyers put down less, pay the insurance for a few years, and refinance it away once they've built equity.
Colorado also has real money on the table to help close the gap. CHFA, the state's housing finance authority, offers a down payment grant of up to $25,000 or 3% of your loan, whichever is less, and it doesn't have to be paid back. If you'd rather borrow the assistance, CHFA's second mortgage option goes up to $25,000 or 4%, with repayment deferred until you sell or refinance. If you're buying in Denver, Adams, Arapahoe, Douglas, or Jefferson County, the NeighborhoodLIFT program can add another $15,000 on top. Denver's own Department of Housing Stability runs a program offering up to 5% of your loan amount as a forgivable loan, as long as you stay in the home for three years. None of these are exotic or hard to find once you know to ask — they're just not the first thing most people hear about.
There's a real, sensible reason 20% still gets recommended: a bigger down payment means a smaller loan, a lower monthly payment, and no mortgage insurance. If you have it and it doesn't wipe out your savings, it's worth considering. But needing it, and it being the only path in, are two different things. I've watched buyers delay for years trying to hit 20%, watching prices climb the whole time, when a 3% or 5% down loan would have gotten them into a house years earlier with the same monthly payment they're paying in rent today.
If you've been sitting on the sidelines because you assumed you needed six figures saved up, it might be worth a conversation before you assume anything else. I'm happy to walk through your options. Let's connect!
 Most mornings, you'll find neighbors out walking their dogs on the old golf course paths. The course closed years ago, the land sat behind a fence for most of that time, and today it's just open — dog walkers, runners, neighbors cutting through on their way somewhere else. It's still bare bones. But it's theirs to walk on, and that's new.
If you live near the old Park Hill Golf Course, or you're thinking about buying in North or Northeast Park Hill, this matters more than it might seem. The park's future just got a lot more certain, and that changes what this land means for the neighborhood around it.
Last November, Denver voters approved the Vibrant Denver bond package, and with it, $70 million dedicated to building out Park Hill Park — the first phase of construction on the 155 acres that used to be the golf course. It's the largest single item in the parks portion of the bond, and once complete, this will be Denver's fourth-largest park. The land opened to the public informally last fall, but this funding is what turns "open field with paths" into an actual, designed park.
The design itself is still being worked out. City planners held an open house at Smith Elementary earlier this year to walk neighbors through a near-final framework for the space — before that, staff had spent months collecting close to 6,000 public comments on what people want here. Ideas on the table include event spaces, a playground, a pool, and art honoring the history of North Park Hill's Black community. Some of the finer details, like how many basketball or tennis courts to include, are still being worked out. But the shape of the park is largely set, and on-site construction is expected to start within the next two years.
For homeowners near the site, this is worth watching closely. A large, well-funded regional park tends to raise interest in the surrounding blocks — new buyers, new foot traffic, sometimes new businesses filling in nearby. That's mostly good news if you own here already. It's also something city planners are aware can push rents and prices up fast enough to squeeze out longtime residents, which is part of why officials have talked about property tax relief and land trust options for the immediate area. If you're a longtime owner near the park, it's worth knowing those conversations are happening, even if the details aren't finalized.
If you're house hunting in Park Hill right now, the park is a real reason to look closely at homes near the site. Proximity to a 155-acre park with $70 million behind it is the kind of thing that tends to matter more in five years than it does today.
If any of this has you thinking about buying near the park, or wondering what it might mean for your home's value if you already live close by, I'm happy to pull the numbers and walk through it with you. Let's connect!


Socials